What if one missed mortgage payment didn't mean losing your home... but ignoring it might?
Your mortgage payment is due?
Maybe you missed one. maybe you've missed two?
The phone starts ringing. A letter arrives from your lender.
Suddenly you're hearing words like default, Notice of Sale, and Power of Sale.
Your first thought?
"Am I going to lose my home?" Take a deep breath.
A Power of Sale is serious, but it doesn't happen overnight. In fact, many Ontario homeowners still have options long before their property is sold.
As a Realtor serving Barrie, Innisfil, Lake Simcoe, and communities throughout Simcoe County, I've spoken with homeowners who felt embarrassed, overwhelmed, or convinced it was already too late.
Often, it wasn't.
Understanding how the process works is the first step toward making informed decisions.
Let's break it down in plain English.
What Is a Power of Sale?
A Power of Sale is the legal process that allows a mortgage lender to sell a property when the homeowner has defaulted on their mortgage.
In Ontario, lenders generally don't have to go through the lengthy court process required in many parts of the United States.
Instead, your mortgage agreement gives the lender the legal right to sell the property if you fail to meet the terms of your mortgage.
The purpose isn't to punish homeowners.
The lender simply wants to recover the money owed on the mortgage.
Power of Sale vs. Foreclosure
These terms are often used interchangeably, but they aren't the same.
Power of Sale (Ontario)
- The homeowner remains the legal owner until the property is sold.
- The lender sells the property to recover the mortgage debt.
- If money remains after the mortgage, legal fees, and selling costs are paid, the remaining equity generally belongs to the homeowner.
Foreclosure
With a foreclosure, the lender takes ownership of the property.
Foreclosures are much less common in Ontario.
Most lenders use the Power of Sale process because it's faster and more efficient.
How Does a Home End Up in Power of Sale?
It usually doesn't happen because someone missed a single payment.
It's more often the result of financial pressure building over time.
Common reasons include:
- Mortgage renewal payment increases
- Job loss
- Divorce or separation
- Illness or disability
- Rising living expenses
- Business income declining
- Unexpected financial emergencies
For many homeowners in Barrie, Innisfil, and Simcoe County, today's higher cost of living combined with mortgage renewal increases has created a level of financial stress they simply weren't expecting.
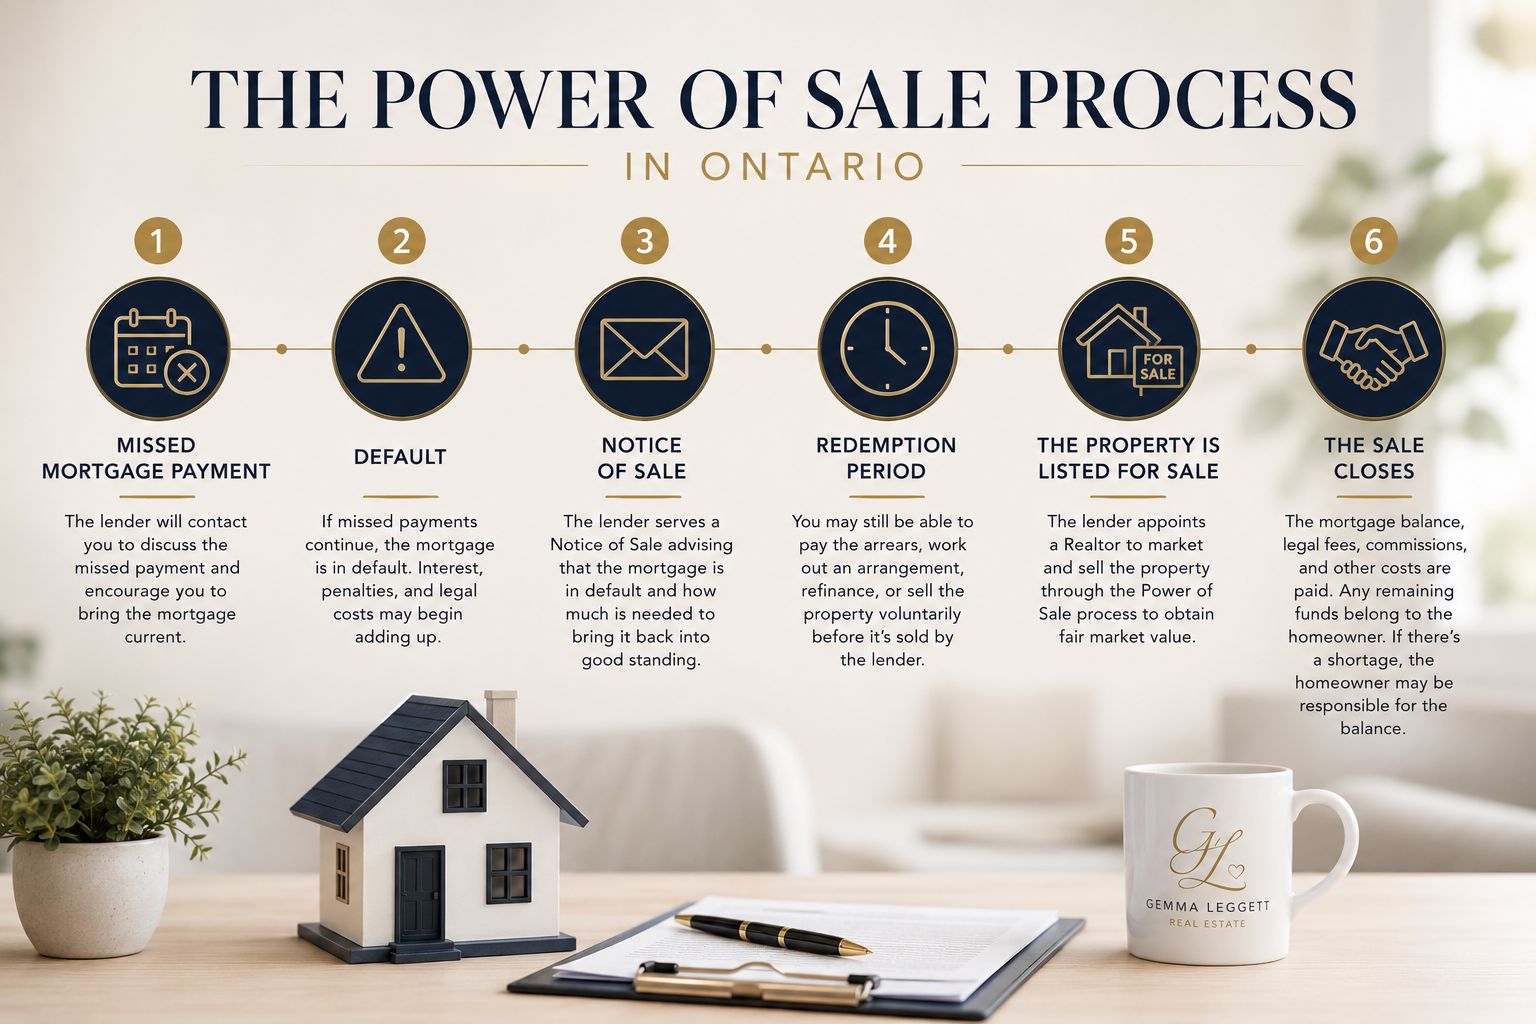
The Power of Sale Process in Ontario
Although every situation is different, the process generally follows the same path.
Step 1: Missed Mortgage Payment
Missing one payment doesn't automatically mean your home is going into Power of Sale. Your lender will usually contact you to discuss the missed payment and encourage you to bring the mortgage current.
This is the best time to communicate. Ignoring phone calls or letters almost never helps.
Step 2: Default
If the missed payments continue, the mortgage is considered to be in default. Interest, penalties, and legal costs may begin adding up.
At this stage, many homeowners still have options.
Step 3: Notice of Sale
The lender serves what's called a Notice of Sale.
This is a formal legal document advising that the mortgage is in default. The notice also explains how much must be paid to bring the mortgage back into good standing.
Many homeowners panic when this letter arrives. Ironically, this is often when they should be asking questions, not giving up.
Step 4: Redemption Period
Ontario provides what's commonly known as the redemption period.
During this time, homeowners may still be able to:
- Pay the mortgage arrears.
- Work out an arrangement with the lender.
- Refinance the mortgage.
- Sell the property voluntarily.
This period gives homeowners one final opportunity to avoid the lender selling the property.
Step 5: The Property Is Listed for Sale
If the mortgage isn't brought back into good standing, the lender appoints a Realtor to market and sell the property through the Power of Sale process.
Contrary to what many people believe, banks don't simply "take" the home or sell it for pennies on the dollar. Under Ontario law, lenders have a legal duty to make reasonable efforts to achieve fair market value when selling a Power of Sale property.
This is why lenders often choose Realtors with experience in Power of Sale sales, local market knowledge, and proven marketing strategies. Proper pricing, professional marketing, and strong negotiation are essential to protecting the lender's interests while attracting qualified buyers.
As a Real Estate Broker serving Barrie, Innisfil, Lake Simcoe, and Simcoe County, I'm proud to have been trusted by lenders to represent Power of Sale property. That experience gave me firsthand knowledge of the process and allows me to guide buyers, homeowners, and financial institutions with confidence and professionalism.
Step 6: The Sale Closes
Once the property sells, the mortgage balance, legal fees, commissions, and other applicable costs are paid.
If money remains, it generally belongs to the homeowner.
If the sale doesn't cover everything owed, the homeowner may still be responsible for the remaining balance.
Can You Stop a Power of Sale?
In many cases...
Yes!
This surprises a lot of homeowners. There are several possible options, depending on your situation.
Catch Up on Missed Payments
If you're able to pay the outstanding mortgage payments, interest, and applicable legal costs before the property sells, the lender generally stops the Power of Sale process.
This is known as redeeming the mortgage.
Work With Your Lender
Many lenders would rather help homeowners find a solution than complete a Power of Sale.
Depending on your circumstances, they may discuss:
- Payment arrangements
- Temporary payment relief
- Revised payment schedules
Every lender is different, but communication matters.
Refinance the Mortgage
Some homeowners qualify for refinancing through another lender.
Others may work with a mortgage broker to explore alternative lending solutions.
This isn't the right answer for everyone, but it's one option worth discussing before assuming there are none.
Sell Before the Bank Does
This is often the option homeowners overlook.
If keeping the home simply isn't realistic, selling the property yourself before the lender completes the Power of Sale process often provides significantly more control.
You may be able to:
- Choose your listing price.
- Negotiate offers.
- Select your closing date.
- Protect more of your equity.
- Minimize long-term credit damage.
Waiting until the lender has already taken over usually reduces those options.
The Biggest Mistakes Homeowners Make
The process itself isn't always what creates the biggest financial loss.
It's waiting too long.
Common mistakes include:
❌ Ignoring letters from the lender.
❌ Assuming one missed payment means it's already over.
❌ Waiting for the market to improve.
❌ Taking advice from friends instead of professionals.
❌ Not understanding how much equity still exists.
The earlier you seek advice, the more choices you typically have.
Should You Call a Realtor Before You're Ready to Sell?
Absolutely.
Many homeowners believe calling a Realtor automatically means putting the house on the market.
It doesn't.
Sometimes the most valuable conversation is simply understanding:
- What your home is worth today.
- How much equity you may have.
- Whether selling voluntarily makes financial sense.
- What other options might be available.
Knowledge creates options.
Local Insight
As a Realtor serving Barrie, Innisfil, Lake Simcoe, and communities throughout Simcoe County, one thing I've learned is that no two Power of Sale situations are ever the same.
Behind every file is a family, a job change, a divorce, a health challenge, or another unexpected life event.
There should never be shame in asking questions.
In many cases, the earlier homeowners seek advice, the more opportunities they have to protect both their home and their financial future.
Frequently Asked Questions
How many missed mortgage payments before a Power of Sale starts?
Every lender is different, but legal action typically begins after the mortgage is in default. Waiting until multiple payments have been missed usually limits your options.
Can I stay in my home during a Power of Sale?
Yes. You remain the legal owner until the property is sold. However, once the sale closes, you'll generally be required to vacate the property.
Will I lose all of my equity?
Not necessarily. If the property sells for more than the amount owed, after legal and selling costs are paid, the remaining equity generally belongs to you.
Can I stop a Power of Sale after receiving a Notice of Sale?
In many cases, yes. Depending on your circumstances, you may be able to redeem the mortgage, refinance, negotiate with your lender, or sell the property before the lender completes the process.
Should I wait to see if things improve?
Generally, the earlier you seek professional advice, the more options you'll have. Waiting can limit those choices and increase legal costs.
You Don't Have to Navigate This Alone
If you're worried about your mortgage, thinking about selling, or simply wondering what your options are, don't wait until the situation becomes overwhelming.
I'm always happy to have a confidential conversation and point you in the right direction. If I can't help directly, I have a trusted network of mortgage brokers, real estate lawyers, financial professionals, and other experts throughout Barrie, Innisfil, Lake Simcoe, and Simcoe County who may be able to help.
Sometimes, understanding your options is the first step toward finding the right solution.
Disclaimer: This article is provided for general educational purposes only and should not be considered legal, financial, or mortgage advice. I am a licensed Real Estate Broker and not a lawyer, mortgage broker, or financial advisor. Every situation is unique. I encourage you to seek advice from qualified professionals before making any financial or legal decisions.