- Submenu for Credit Score Affects You
- HOW TO BUY A HOUSE?
- FHSA
- Credit Score Affects You
- Calculators
- Save on Interest
- Avoid Money Pit
- 5 Costly Mistakes
- Buyer's Guide
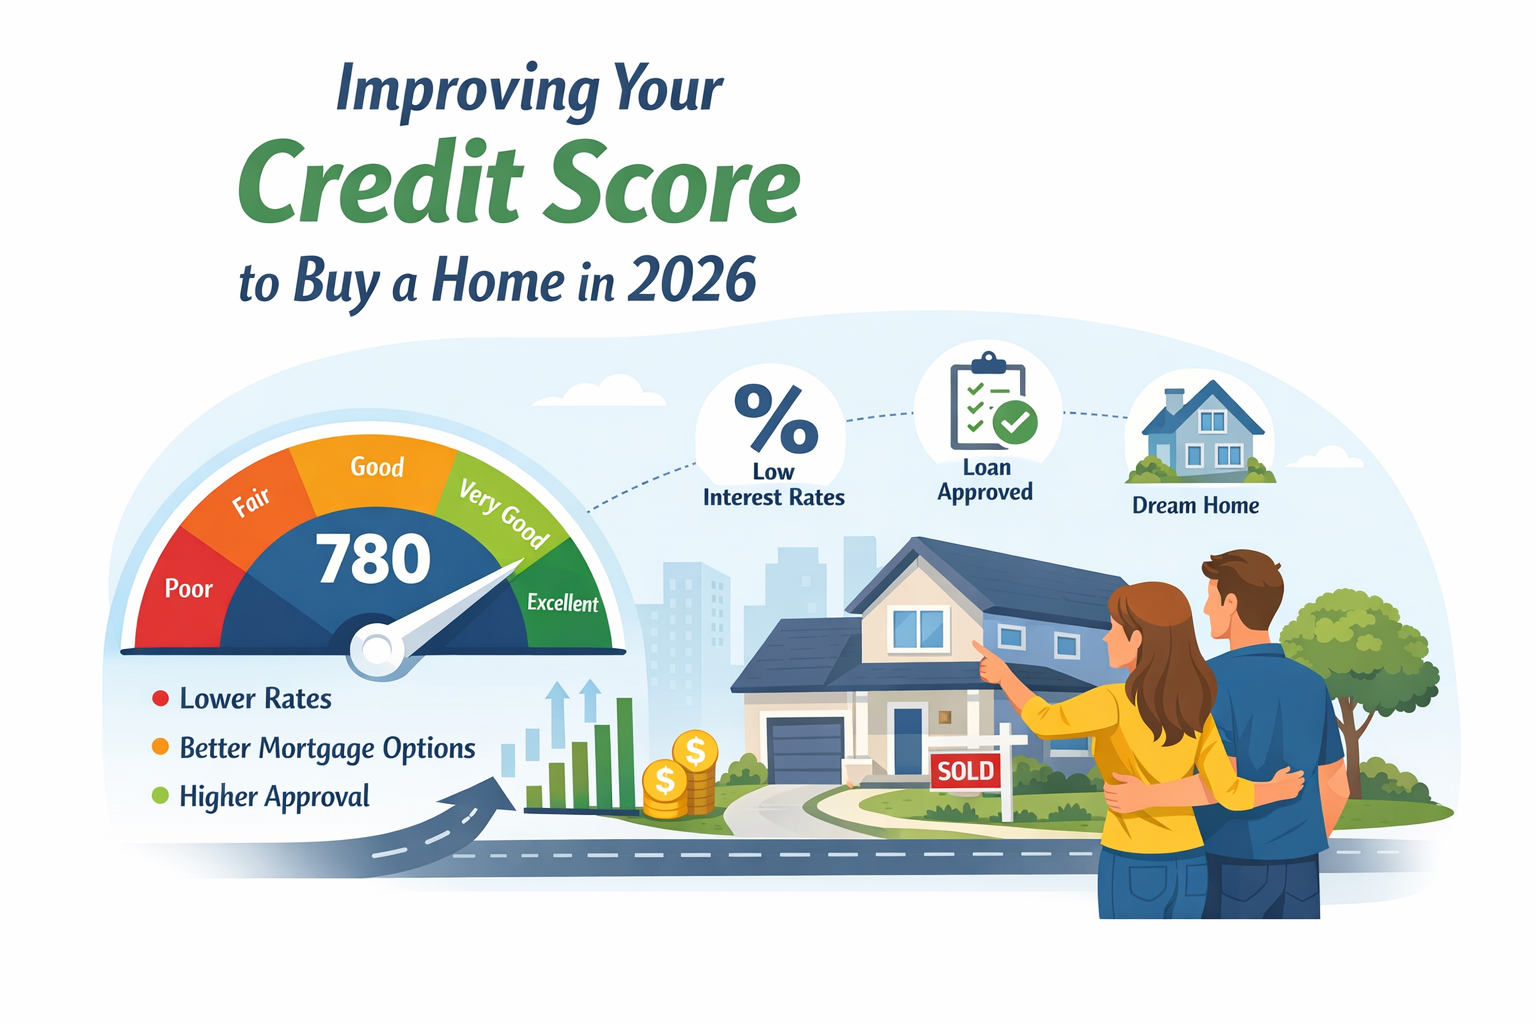
Let’s clear something up right away:
👉 Your credit score doesn’t decide if you can buy a home — it influences how easily and how affordably you can.
In 2026, lenders rely heavily on your credit profile to determine:
✅ How much you can borrow
💰 What interest rate you qualify for
📉 Whether mortgage insurance is required
🚪 Which programs are even available to you
But here’s the part no one tells you:
Credit scores are fixable. Strategic. And often misunderstood.
Let’s break it down — no finance jargon, no fear tactics.
Your credit score is a number — typically between 300 and 900 in Canada — that tells lenders how risky it is to lend you money.
It’s calculated using:
💳 Payment history (do you pay on time?)
📉 Credit utilization (how much of your available credit you’re using)
⏳ Length of credit history
🔁 Credit mix (cards, loans, lines of credit)
🔍 Recent credit inquiries
Higher score = lower risk = better mortgage options.
💡 Think of your credit score like a résumé for borrowing money.
(Insert visual bar graph here)
| Credit Score | What Lenders See | What It Means for You |
|---|---|---|
| 760+ | Excellent | Best rates & flexibility |
| 700–759 | Very Good | Strong approval odds |
| 660–699 | Good | Most programs available |
| 600–659 | Fair | Higher rates / tighter rules |
| Below 600 | Challenging | Still possible — with planning |
✨ Good news: Many buyers think they need “perfect credit.”
They don’t.
Mortgage rules have tightened, rates fluctuate, and lenders want predictability.
Your credit score helps them answer one question:
“Is this borrower likely to pay us back, on time, every month?”
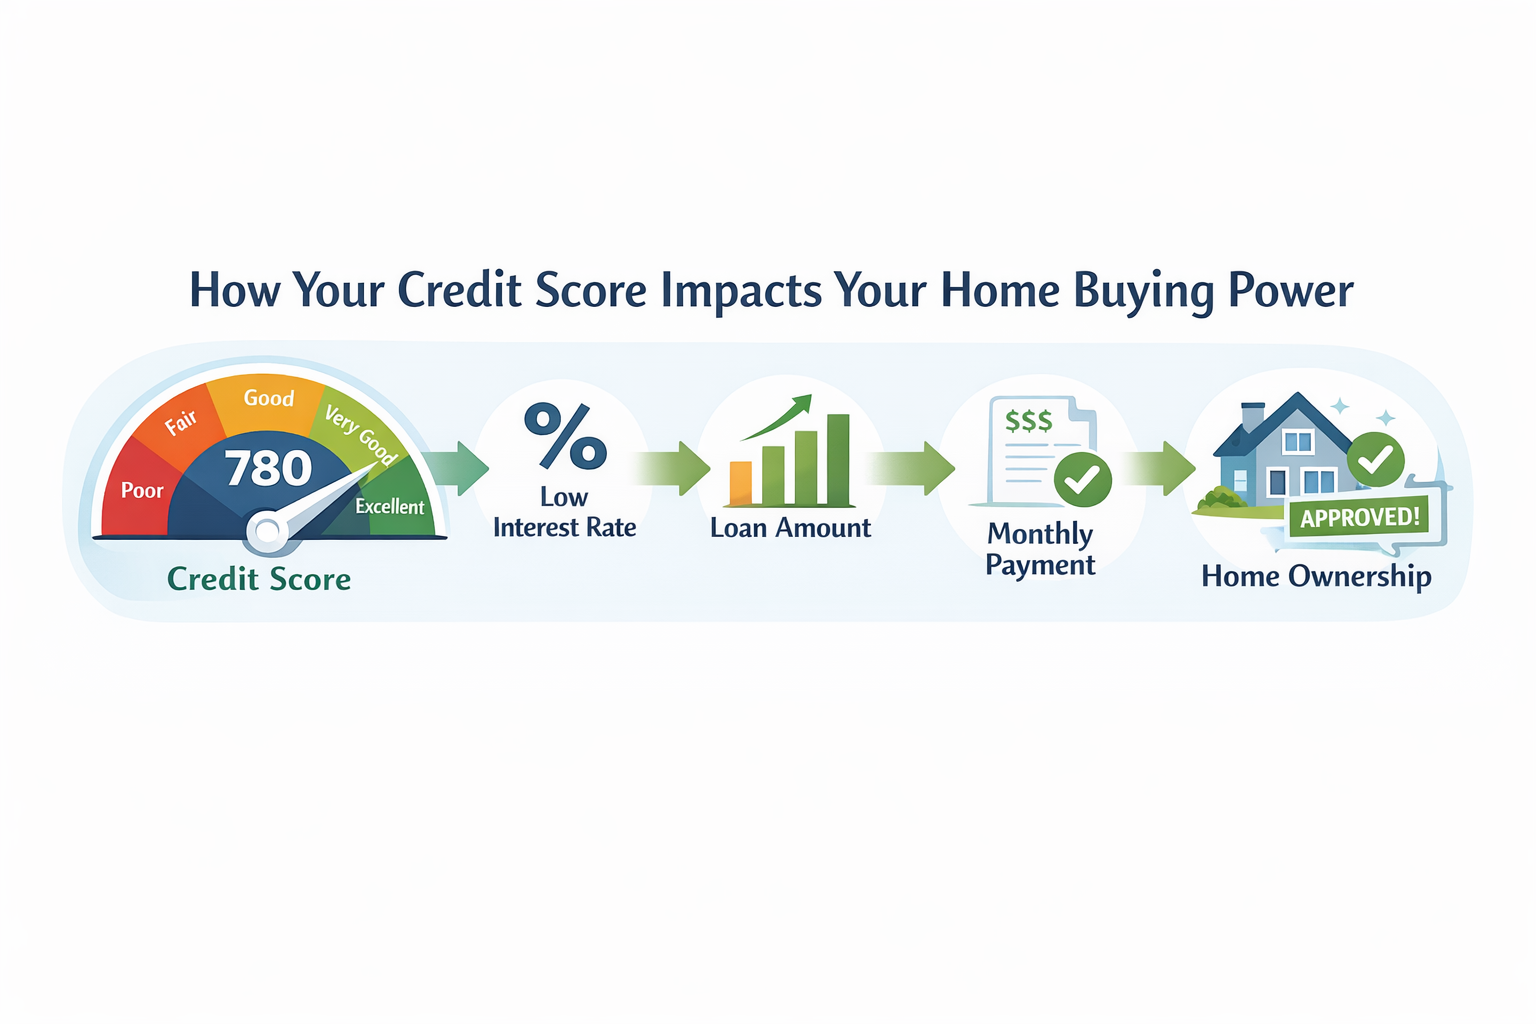
That score influences:
Your interest rate
Your monthly payment
Whether CMHC mortgage insurance is required
How much wiggle room you have in negotiations
Even a small improvement in your score can save you tens of thousands of dollars over the life of a mortgage.
🚫 Applying for new credit right before buying
🚫 Financing a car or furniture pre-closing
🚫 “No payments for 12 months” store offers
🚫 Maxing out cards to “use rewards”
🚫 Closing old credit accounts
💬 Gemma Tip:
Your credit score can drop just from asking for credit. Lenders see that as uncertainty — and uncertainty costs money.
Here’s what actually works:
✔ Pay every bill on time (even the small ones)
✔ Keep credit card balances under 30% of limits
✔ Avoid new credit applications
✔ Don’t co-sign loans for anyone (even family 😬)
✔ Check your credit report for errors
⏱ Even 60–90 days of smart behaviour can improve your score.
I get it. New house = new couch.
But timing matters.
👉 Buy the house first. Then the furniture.
Once you own, you may qualify for:
Home equity options
Better interest rates
Tax-efficient borrowing
Before closing? That same purchase could derail your approval.
Your credit score is not a judgment of you.
It’s a snapshot — and snapshots can be updated.
I’ve helped buyers with:
New credit history
Past bankruptcies
Divorce-related credit damage
Self-employed income
One “oops” year that haunted them
The key is strategy, not panic.
I don’t just unlock doors — I help you:
Understand what lenders actually care about
Connect with trusted mortgage professionals
Create a realistic game plan (even if buying isn’t this month)
Avoid mistakes that cost approvals
Sometimes the smartest move is waiting.
Sometimes it’s acting quickly.
Either way — you deserve clarity.
If you’re thinking about buying in Innisfil, Barrie, Simcoe County, or York Region, let’s chat.
📩 I’ll help you understand:
Where you stand
What’s possible
What steps (if any) to take next
No sales pitch. Just real advice.
Because the best buyers aren’t perfect — they’re prepared. 💪🏡
Most buyers can qualify with a credit score of at least 600–660, depending on the lender and mortgage program.
Higher scores typically mean better interest rates and more flexibility, but perfect credit is not required.
Yes — in many cases.
Buyers with past credit challenges (late payments, collections, bankruptcy, divorce-related debt) may still qualify with:
Higher down payments
Alternative lenders
A short credit improvement plan
💬 The key is strategy, not giving up.
Absolutely. Your credit score impacts:
Your interest rate
Your monthly payment
Whether mortgage insurance is required
Even a small difference in score can change your buying power by tens of thousands of dollars.
No.
Checking your own credit score is considered a soft inquiry and does not affect your score.
⚠️ Applying for new credit, however, can lower it.
Ideally, 3–6 months before purchasing.
This includes:
Credit cards
Car loans
Store financing
Lines of credit
💡 Stability is your best friend when lenders review your file.
Not always.
Sometimes paying off certain debts can actually lower your score temporarily.
👉 This is why speaking to a mortgage professional before making big moves is critical.
Yes — especially if you’re using more than 30% of your available credit.
✔ Small balances paid on time are okay
🚫 Maxed-out cards are not
Typically, yes.
Lower scores often mean:
Higher interest rates
Less lender flexibility
Stricter approval conditions
But there are ways to improve this with planning.
Yes.
First-time buyers may still qualify using:
Insured mortgages (CMHC, Sagen, Canada Guaranty)
Gifted down payments
Co-borrowers
Each situation is unique.
It can — but it comes with risks for both parties.
A co-signer’s credit and income are fully tied to the mortgage.
⚠️ This should always be discussed carefully.
Some improvements happen in 30–90 days, especially by:
Paying balances down
Fixing errors on your credit report
Avoiding new inquiries
Others take longer — and that’s okay.
Usually, no.
Closing older accounts can shorten your credit history and lower your score.
💬 Old, well-managed credit is valuable.
Before you start house hunting.
Early conversations help you:
Avoid costly mistakes
Understand your true buying power
Create a confident, realistic plan
No pressure. Just clarity.
Yes — and that’s often the smartest place to start.
I help buyers:
Understand where they stand
Connect with trusted mortgage pros
Build a clear roadmap (even if buying is months away)
Buying a home isn’t about perfection — it’s about preparation.
If you’re considering buying in Innisfil, Simcoe County, or York Region, I’m happy to walk through your situation and help you understand your options.
Knowledge first. Pressure never. 🏡✨
I’m your local awesome realtor, not a mortgage broker. I can guide you through the home buying process, explain the basics of mortgage types, and connect you with trusted mortgage professionals to get the best rates!