- Submenu for Save on Interest
- HOW TO BUY A HOUSE?
- FHSA
- Credit Score Affects You
- Calculators
- Save on Interest
- Avoid Money Pit
- 5 Costly Mistakes
- Buyer's Guide
Owning a home is amazing — but no one likes giving extra money to the bank in interest. The good news? There are smart, simple ways to shave years off your mortgage and save tens of thousands of dollars — without living on ramen noodles.
Here’s how.
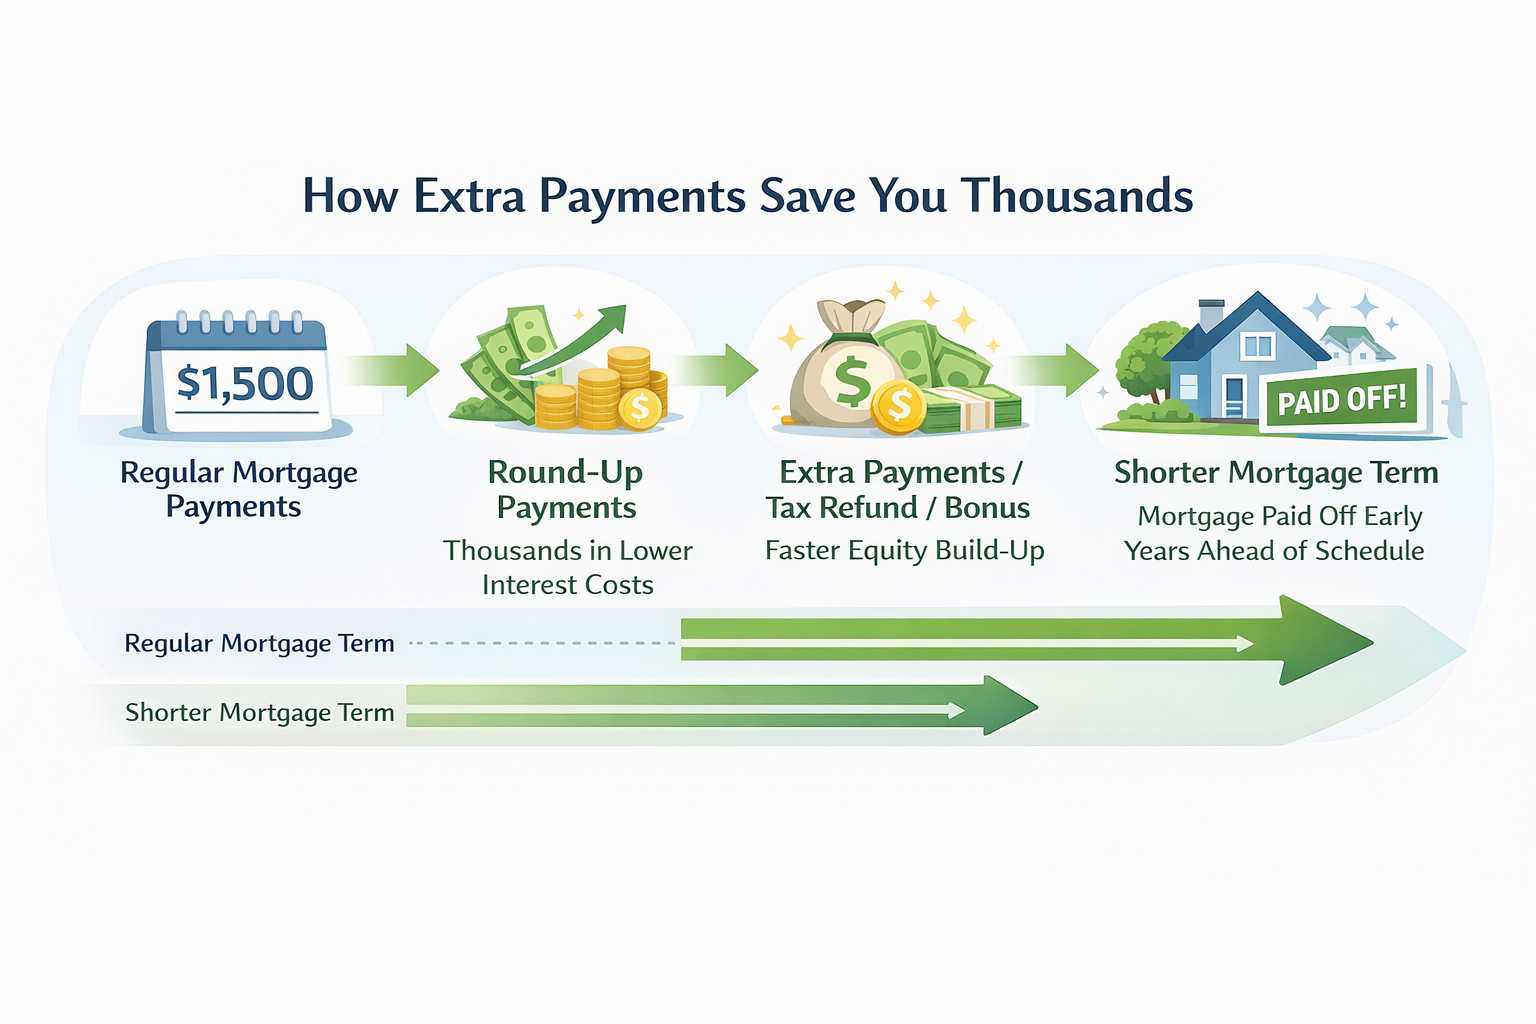
It’s ridiculously simple: instead of paying the exact mortgage amount, round it up.
Example:
Your mortgage: $734/month
Round up to: $800/month
Result: Save $48,000+ in interest and pay off your mortgage 7.5 years sooner
💡 Gemma Tip: Even rounding up $20–$50 can make a noticeable difference over time. Every little bit counts!
Got a refund, bonus, or extra cash this year? Don’t let it sit in your account — put it straight on your mortgage principal.
Example:
Mortgage: $100,000
Tax refund applied: $1,000
Result: Save $8,600+ in interest and shave 1 year & 1 month off your mortgage
💬 Think of it as a “gift to future-you.” Your bank won’t mind 😉
If your budget allows, choosing a 15-year term instead of 30 can save a fortune.
Example:
Mortgage: $100,000 at 8% interest
Monthly payment: +$200
Interest saved: $92,000+ over the life of the loan
💡 Yes, the payment is slightly higher — but the payoff is freedom years sooner and huge interest savings.
Make extra payments whenever possible (even $50–$100 a month adds up)
Refinance when rates drop (but watch fees!)
Use windfalls, like work bonuses or inheritance, to crush your principal
The best part? These strategies are simple, legal, and totally under your control.
Mortgage interest is front-loaded — meaning early payments mostly go to interest. Every extra dollar you apply to the principal now saves you even more interest later.
(Here you could add a visual graph showing: “Extra Payment → Principal Paid → Interest Saved → Mortgage Term Shortened”)
Round up payments — small changes make big differences
Prepay principal with extra cash
Consider shorter mortgage terms for long-term savings
Every little extra counts — it’s like a cheat code for homeowners
If you’re in Innisfil, Simcoe County, or York Region, I can help you:
See exactly how much you could save
Plan extra payments without breaking your budget
Make your mortgage work for you, not the bank
Knowledge first, stress never. 💪🏡
Q1: Will rounding up my monthly payment really make a difference?
Yes! Even small amounts like $20–$50 a month reduce your principal faster, saving thousands in interest and cutting years off your mortgage.
Q2: Can I make extra payments without penalty?
Most mortgages allow prepayments up to a certain percentage each year without penalty. Always check your mortgage agreement or ask your lender, it’s often easier than you think.
Q3: Is it worth using my tax refund or bonus to pay down my mortgage?
Absolutely. Extra principal payments directly reduce interest over time. Even $1,000 can save you thousands in the long run.
Q4: Should I switch to a 15-year mortgage?
If your budget allows, yes. Shorter-term mortgages cost a bit more monthly, but the interest savings are huge — sometimes tens of thousands of dollars.
Q5: How does extra payment timing affect savings?
The earlier you pay extra toward principal, the more interest you save. Early payments have the biggest impact because mortgages are front-loaded with interest.
Q6: Can small extra payments really shorten my mortgage by years?
Yes! Even small regular extra payments can shave 3–5 years or more, depending on your mortgage size and interest rate.
Q7: Are there risks to paying extra on my mortgage?
Minimal. Just make sure you maintain an emergency fund. Extra payments are great, but you don’t want to drain your cash flow and cause stress.
Q8: How often should I prepay?
Whenever you have extra cash — monthly, quarterly, or yearly. Even irregular payments make a noticeable difference over time.
Q9: Can refinancing help me pay off my mortgage faster?
Yes, if rates drop and fees are reasonable. You can also refinance to a shorter-term mortgage, but always calculate the total interest savings vs. cost.
📌 Disclaimer:
I am a real estate broker, not a mortgage broker. I can provide guidance on strategies to pay off your mortgage faster and connect you with trusted mortgage professionals, but I cannot provide mortgage rates, advice or approval decisions. Always confirm any mortgage-specific actions with your lender or mortgage broker.